
Before you read on: If your Self Assessment bill is over £1,000, HMRC asks for the year’s tax plus half of it again as an advance on next year, both due on 31 January, and a second advance on 31 July. Payments on account are next year’s tax paid early rather than an extra charge, and first-time filers get caught out constantly.
Table of Contents
Nothing about a first tax bill causes as much panic as this one. You do the sums, you save up what you think you owe, you log in on 30 January, and the number on screen is half again as big as the one in your head. Here’s exactly what’s going on.
Payments on account explained: what it is
HMRC assumes next year will look roughly like this one. Rather than wait twelve months for the money, it collects next year’s tax in two instalments, in advance. Each instalment is half of this year’s bill.
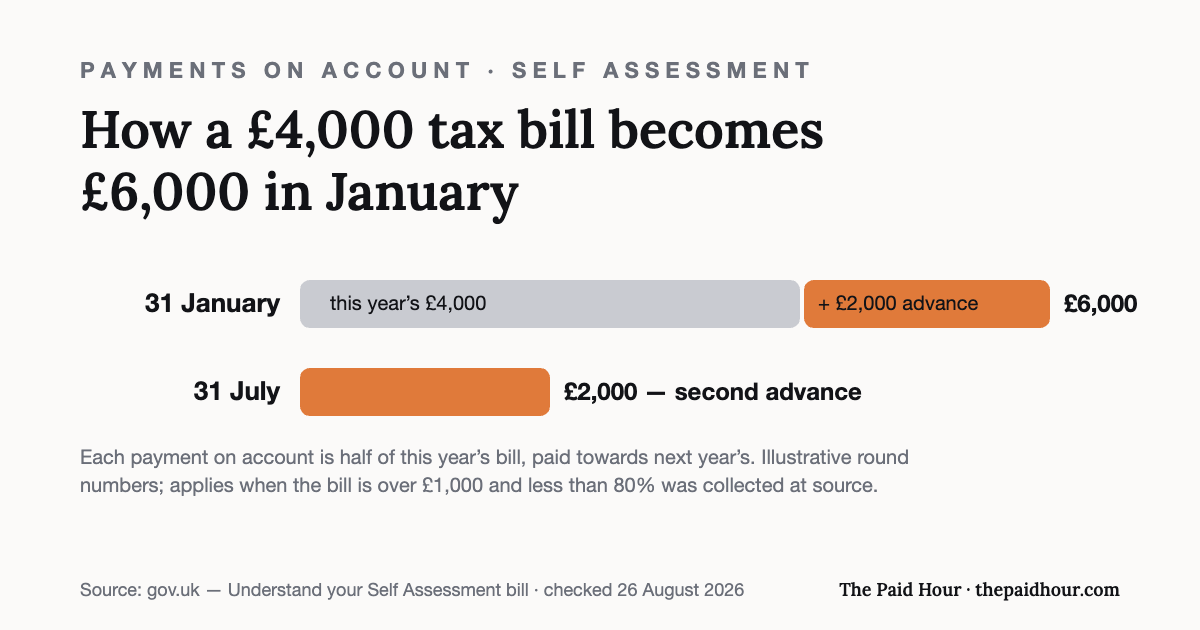
How a £4,000 bill becomes £6,000 in January. Illustrative example, worked through with round numbers. Say your bill for the year is £4,000.
- 31 January: £4,000 for the year just gone, plus £2,000 as the first payment on account for the next year. Total £6,000.
- 31 July: the second payment on account, another £2,000.
- The following 31 January: your actual bill for that year, minus the £4,000 you’ve already paid in advance. Plus the first payment on account for the year after that.
After the first year it settles into a rhythm. It’s only that first January that really hurts, because you’re paying a full year and a half at once.
When you have to make payments on account
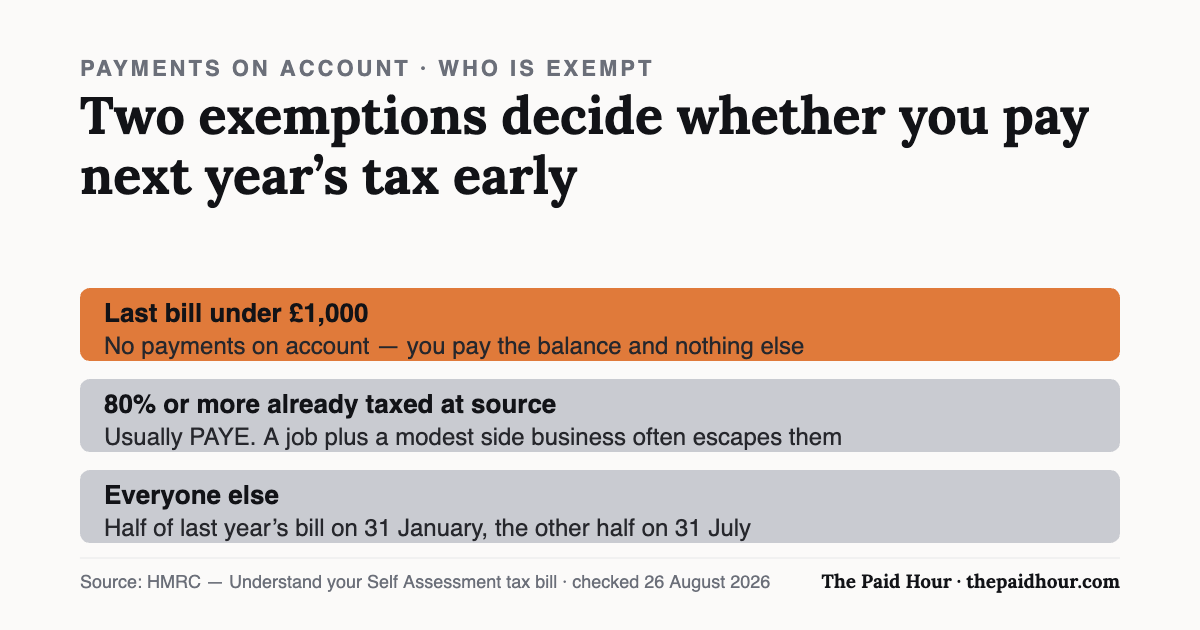
You make payments on account unless one of two things is true: your last bill was under £1,000, or more than 80% of your tax was already collected at source, typically through PAYE. HMRC sets this out on payments on account.
So someone with a full-time job and a modest side business often escapes them entirely. Someone who’s fully self-employed and earning well almost certainly won’t.
The trap nobody warns you about
The advance is based on last year. If this year’s worse (you lost a big client, took time off, went part-time), you’re still being asked to pay as if it were just as good as last year.
You can ask HMRC to reduce your payments on account if you expect to earn less. Be careful though: reduce them too far and end up owing more, and HMRC charges interest on the shortfall from the original due date. Reduce them because you’ve got a realistic forecast, not just because January is expensive.
Payments on account: what to actually do about it
- Work out your bill before January. Don’t wait for HMRC to tell you, you can estimate it at any point.
- Assume 150% in year one. If you think you owe £4,000, put aside £6,000. Anything left over is a bonus rather than a crisis.
- Move money as you earn it. A separate savings account and a fixed percentage of every invoice (many freelancers use 25–30%), turns the January bill into a transfer instead of an emergency.
- Remember 31 July exists. The second instalment catches people who’ve mentally filed tax under “done for the year”.
- If you can’t pay, talk to HMRC. There’s a process for payment plans, and it goes far better before the deadline than after.
Can you reduce them if this year looks worse?
Yes. Payments on account are HMRC’s guess, and the guess is last year’s bill. If your income is falling (a lost client, a quieter six months, a stretch off work), you can ask HMRC to lower both instalments, online from your Self Assessment account or by post on form SA303, any time up to 31 January after the tax year ends.
The trade-off: reduce too far and HMRC charges late payment interest on the shortfall, back-dated to the original due dates: 7.75% at the time of checking, and a reduction made with no real basis can attract a penalty. The full walk-through, the interest arithmetic and the mistakes to avoid are in how to reduce your payments on account with form SA303.
Does Making Tax Digital change this?
No. Quarterly updates under Making Tax Digital are summaries of income and expenses, they don’t calculate or collect tax. The payment dates stay the same: 31 January and 31 July. See what Making Tax Digital changes.
If this is your first return, our guide to filing your first Self Assessment covers the full sequence of deadlines.
Your MTD ITSA start date is decided by an earlier tax year’s qualifying income. Source: HMRC, checked 19 August 2026.
Related: self-employed National Insurance in 2026/27: Class 4 sits on top of the Income Tax you’re budgeting for here.
Two things make the January number easier to live with. Setting the money aside as you earn it is the obvious one, and how much to put aside, worked out from the actual 2026/27 rates does the arithmetic instead of repeating the usual flat percentage. If the bill has already landed and the money is not there, HMRC Time to Pay spreads it over instalments instead of leaving it to sit.
Common questions about payments on account
Do payments on account mean I am taxed twice?
No. They are next year’s tax paid early rather than an extra charge. The following January, everything you have already paid in advance comes off the bill for that year, and only the difference is due. It feels like a double charge exactly once — in the first January, when a full year and a half land together.
Who does not have to make payments on account?
Two exemptions. Your last bill was under £1,000, or more than 80% of your tax was already collected at source, usually through PAYE. So someone with a full-time job and a modest side business often escapes them entirely, while someone fully self-employed and earning well almost certainly does not.
What if this year is worse than last year?
You can ask HMRC to lower both instalments (online from your Self Assessment account, or by post on form SA303), any time up to 31 January after the tax year ends. The trade-off is real: reduce too far and HMRC charges late payment interest on the shortfall, back-dated to the original due dates, and a reduction with no genuine basis can attract a penalty.
When exactly are payments on account due?
31 January, alongside the balancing payment for the year just gone, and 31 July. The July instalment is the one people forget, because by then tax feels filed and finished. It is the same amount as the January advance, and it is not optional.
Does Making Tax Digital change the payment dates?
No. Quarterly updates under Making Tax Digital are summaries of income and expenses, nothing is calculated from them and nothing becomes payable. The dates stay 31 January and 31 July, exactly as before.
What if the money is not there on 31 January?
Talk to HMRC rather than letting the date pass. There is a process for spreading the bill over instalments, and it goes considerably better before the deadline than after, a payment on account you have flagged in advance is a very different conversation from one you have simply missed.
How much should I set aside so January is not a shock?
In the first year, assume 150% of what you think you owe: if the bill looks like £4,000, put £6,000 aside. After that the rhythm settles. Moving a fixed share of every invoice (many freelancers use 25–30%), into a separate savings account as it arrives turns the January payment into a transfer instead of an emergency.
Filing it yourself this year?
HMRC Tax & Expense Mastery 2026/27. Nine modules and eleven working templates that take a UK freelancer from “do I even need to register” to a correct return, with MTD quarters built in.
- Fifteen expense categories, with the trap inside each one (training, clothing, meals, the seven-year pre-trading rule)
- Home and vehicle: flat rate against actual cost, with the £312 break-even worked out and the mileage lock-in rule
- The year-one payments-on-account cash shock, and the routine that stops it landing twice
HMRC does not send a list of what you forgot to claim. Most freelancers leave several hundred pounds of legitimate expenses on the table every single year, and the return still gets filed.
Buying more than one? The Complete Freelancer System, all five for £87, against £215 at full price.
Need this ready-made? → Self Assessment Prep Checklist Pack. Every deadline, record and allowance in 9 pages (£7.99, instant download)
Sources
- HMRC, Understand your Self Assessment tax bill: payments on account
- HMRC: Self Assessment deadlines
- HMRC, If you cannot pay your tax bill on time
The SA303 claim route and the 7.75% late payment interest rate read from gov.uk on 26 August 2026. The mechanics re-checked against gov.uk on 26 August 2026; the £4,000 example is the post’s own illustrative arithmetic.
Checked against HMRC guidance on 19 August 2026. General information, not tax advice, for your own position, speak to a qualified accountant.
The 31 January and 31 July payment dates in context, with everything else the year throws at you: the 2026/27 tax year calendar.