
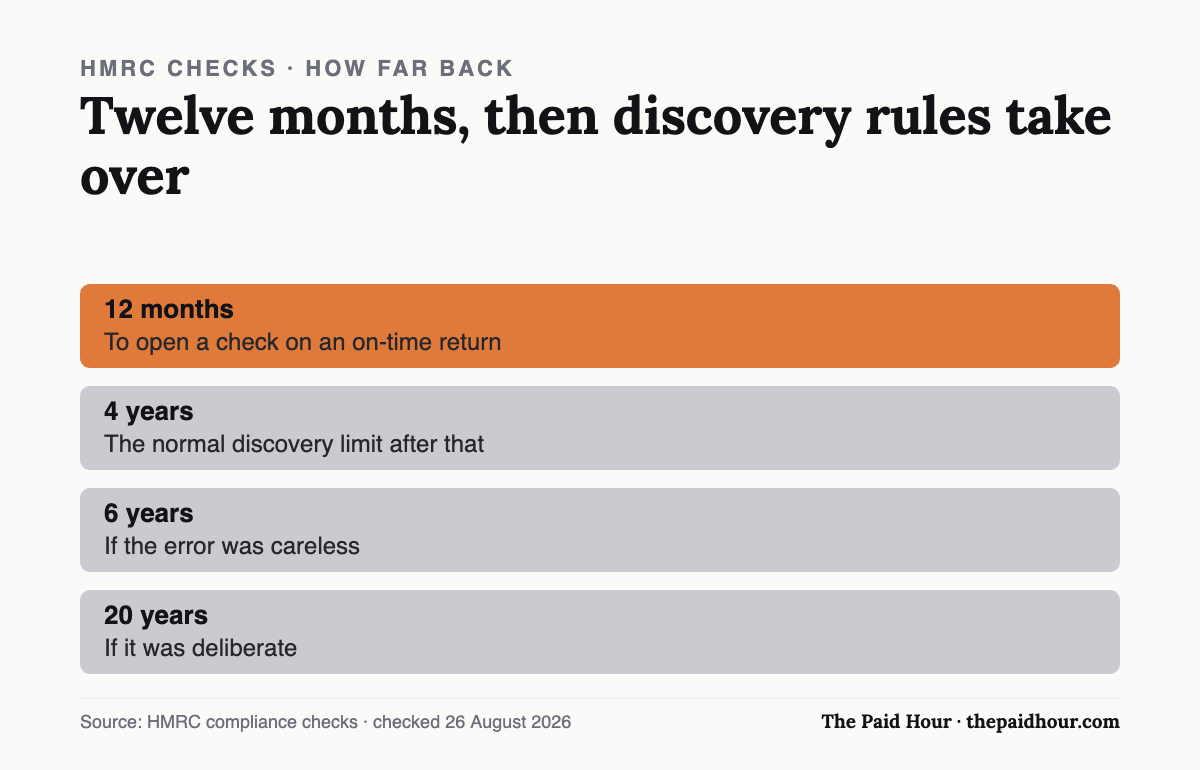
What matters here: HMRC calls it a compliance check. If you filed on time, it has 12 months from the date your return was received to open one. After that window shuts it needs a discovery, and the limits are 4 years normally, 6 if the error was careless and 20 if it was deliberate. Most checks are narrow, most are dull, and a fair number land on returns with nothing wrong in them at all.
Table of Contents
An HMRC enquiry into your tax return is a formal process with published time limits and, usually, a mundane explanation behind it. The letter does not read that way. Plenty of freelancers panic first and read it properly second, which is the wrong order, because the letter itself tells you how narrow or broad the thing is.
Most self-employed people never get one.
What an HMRC enquiry is actually called
The gov.uk term is a compliance check, and it can cover your Self Assessment return, your accounts and tax calculations, or any tax you pay. HMRC writes or phones to tell you what it wants to look at. You will not find out some other way, and a check can end with nothing owed, a refund, or extra tax due.
The HMRC enquiry window: how long they have
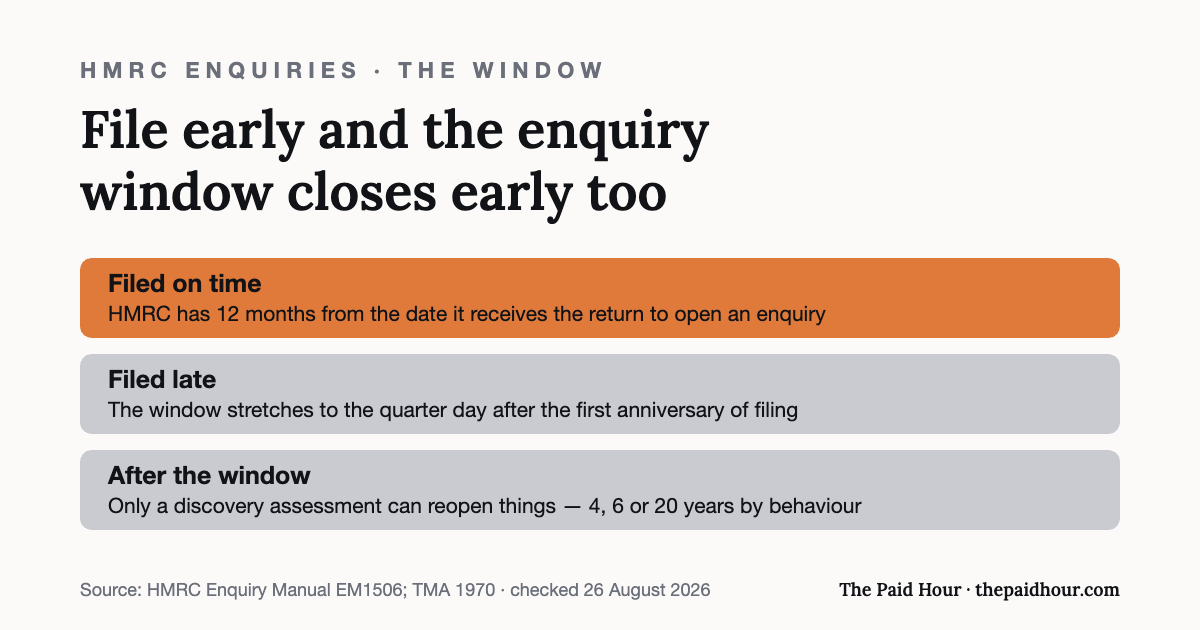
This is the part almost nobody knows, and it is the most useful thing in this post. Under section 9A(2) of the Taxes Management Act 1970, where a return arrives on or before its filing deadline, HMRC’s Enquiry Manual is explicit that “the enquiry window will run for a full 12 months from the date the tax return is received”.
From the date it was received, not from 31 January. Filing early therefore starts the clock early. File your 2025/26 return on 20 November 2026 and the window closes on 20 November 2027, two and a half months before someone who filed on the deadline.
File late and the rule changes. The window then runs to the quarter day following the first anniversary of the day the return was made, the quarter days being 31 January, 30 April, 31 July and 31 October. A return sent on 10 March 2027 has its first anniversary on 10 March 2028, so the window does not shut until 30 April 2028. Filing late costs you a penalty and hands HMRC extra time.
After the window closes: discovery assessments
A closed enquiry window is not the same as a closed file. If HMRC later discovers that tax has been lost, it can raise an assessment outside the window, and the time limit it gets depends on how the loss came about.
| How the tax came to be lost | Time limit | Counted from |
|---|---|---|
| Ordinary case | 4 years | The end of the tax year |
| Brought about carelessly | 6 years | The end of the tax year |
| Brought about deliberately | 20 years | The end of the tax year |
Those sit in sections 34 and 36 of the same Act. The jump from six years to twenty is the whole reason the word “careless” matters so much in any correspondence with HMRC, it is not a softer synonym for deliberate, it is a different statutory box with a different clock.
It also explains the record-keeping rule. You are asked to keep records for five years after the 31 January deadline of the relevant tax year, which is roughly the ordinary assessment window plus a margin. Keeping them for the six-year careless limit costs nothing extra if they are digital.
Aspect or full: two kinds of HMRC enquiry
An aspect enquiry looks at one specific part of the return: an expense claim that looks out of proportion to turnover, or a figure that does not match what a client or platform has reported. A full enquiry looks at the whole return and sometimes at your wider financial position.
Aspect enquiries are much more common and much less painful. HMRC has one question, you answer it with evidence, and it closes.
What triggers an HMRC enquiry
HMRC does not publish a checklist, and anyone selling you the exact algorithm is guessing. What is well understood is that returns draw attention more often when:
- Figures move sharply year to year with nothing on the return to explain it.
- Expenses look high against turnover for that line of work.
- Reported income does not match third-party data HMRC already holds, a client’s own return, a digital platform’s reporting, bank interest.
- The return is picked at random as part of routine compliance activity.
That last one is worth sitting with. A share of enquiries land on completely honest returns for reasons connected to nothing the taxpayer did. Being selected is not an accusation.
What happens during an HMRC enquiry
HMRC may ask to see records, ask you to visit them, or ask to visit your home, your business or your adviser’s office. You can have an accountant or adviser with you, and most people facing anything beyond a simple aspect query do.
Ignoring an inspection or an information notice carries a penalty of its own. There is a reasonable excuse let-out: serious illness or a bereavement, for instance, but not wanting to is not one. If you disagree with the outcome you can appeal the decision, and you can apply for alternative dispute resolution at any point, including while the check is still running.
What it costs if something is wrong
Penalties for an inaccuracy are set as a percentage of the extra tax, and the percentage depends on two things: how the error happened, and whether you told HMRC before they asked. HMRC’s Compliance Handbook puts the range for an unprompted careless inaccuracy on an onshore matter at 0% to 30%. Prompted disclosures and deliberate behaviour sit in higher ranges.
Nought per cent is a real outcome rather than a theoretical floor. Which is the argument for correcting a mistake the week you spot it rather than hoping it goes unnoticed for four years.
The HMRC enquiry letter has arrived. What now?
Read it properly first. It says what HMRC wants to check, which tells you immediately whether this is one line of your return or the whole thing.
Then send exactly what was asked for and nothing more. A scattergun response invites more questions instead of fewer. Where the figure has a straightforward explanation, a clear written answer with the paperwork behind it usually closes an aspect enquiry without drama. Where it does not, or where the letter describes a full enquiry, that is the point to bring in an accountant rather than handle it alone.
Records kept as you go,, not reconstructed a year later, are what make a check short and boring. If the letter has also left you unsure about filing dates, the Self Assessment deadlines guide and the 2026/27 tax year calendar cover those.
Want the whole tax system, not one rule?
HMRC Tax & Expense Mastery 2026/27. Nine modules and eleven working templates that take a UK freelancer from “do I even need to register” to a correct return, with MTD quarters built in.
- Fifteen expense categories, with the trap inside each one (training, clothing, meals, the seven-year pre-trading rule)
- Home and vehicle: flat rate against actual cost, with the £312 break-even worked out and the mileage lock-in rule
- The year-one payments-on-account cash shock, and the routine that stops it landing twice
HMRC does not send a list of what you forgot to claim. Most freelancers leave several hundred pounds of legitimate expenses on the table every single year, and the return still gets filed.
Buying more than one? The Complete Freelancer System, all five for £87, against £215 at full price.
Need this ready-made? → Self Assessment Prep Checklist Pack — every deadline, record and allowance in 9 pages (£7.99, instant download)
Sources
- gov.uk, Tax compliance checks
- HMRC Enquiry Manual EM1506, the enquiry window
- HMRC Enquiry Manual EM3214, discovery assessment time limits
- Taxes Management Act 1970, section 9A: notice of enquiry
- Taxes Management Act 1970, section 36, loss of tax brought about carelessly or deliberately
- HMRC Compliance Handbook CH82465. Penalty ranges for inaccuracies
- gov.uk, How long to keep your records
The enquiry-window rule was re-checked against HMRC’s Enquiry Manual (EM1506) on 26 August 2026.
Every rule and time limit above was checked against gov.uk and legislation.gov.uk on 25 August 2026. This is general information about how compliance checks work, not tax advice. If you have received a letter, speak to an accountant.