
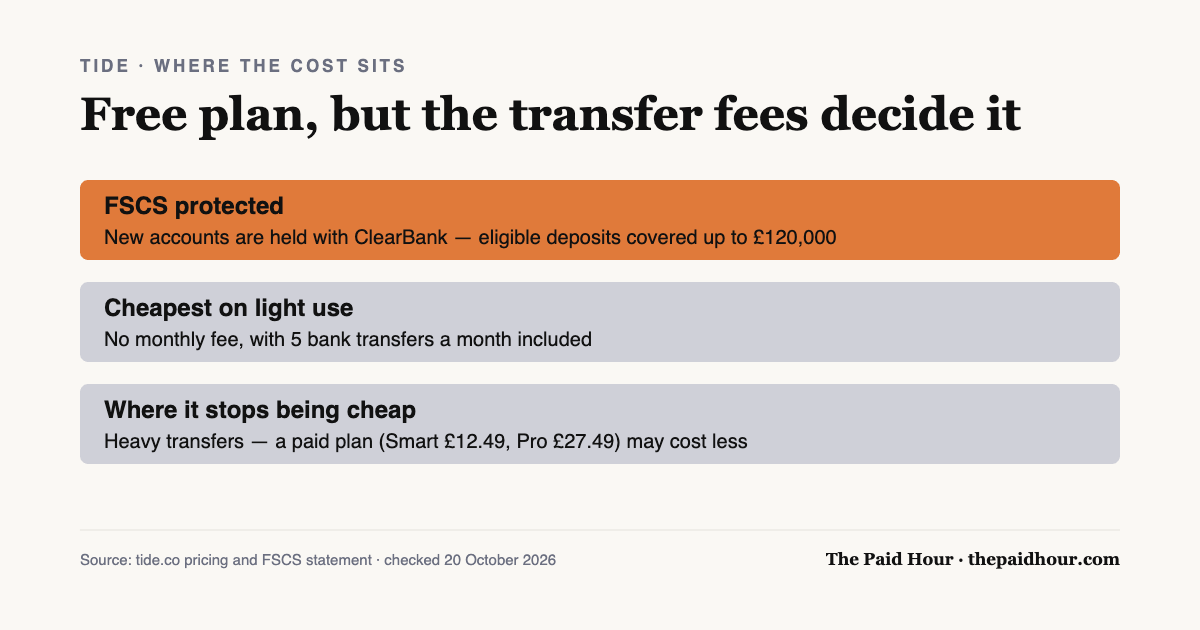
Tide is not a bank. New business current accounts are provided by ClearBank, so eligible deposits are FSCS protected up to £120,000. The free plan works, but read the transfer limits before signing up: light use is where Tide is cheapest, and heavy monthly transfers are where the fees quietly stack.
Search for a Tide business account review and most results just restate Tide’s own pricing table and call it a day. This one goes a step further: we’ve worked out what the fees cost a typical UK freelancer month to month, and we’ve checked the one thing most reviews get wrong or leave stale. How your money is protected, and by how much, as of right now.
Quick verdict: Tide is a solid free-to-start option if you make five or fewer transfers a month and don’t need to send more than three invoices. Past that, the paid tiers are competitive on invoicing and savings rates but you should do the sums for your own volume before assuming the free plan is “free enough.” We’ve already flagged in our best business bank accounts for UK sole traders guide that Starling suits most sole traders better by default, this review explains exactly when Tide is the better call instead. If you’re still deciding whether you need a dedicated business account at all as a sole trader, start here.
What the Tide business account actually is (and isn’t)
Tide is not a bank: it’s a business financial platform, authorised by the FCA as an e-money institution. New business current accounts are provided by its banking partner, ClearBank Ltd, which is why eligible deposits get the FSCS protection described below. This distinction matters less day-to-day than it sounds, but it’s worth knowing before you read “bank account” anywhere on Tide’s marketing. That distinction matters for anyone comparing this Tide business account review against a traditional bank’s small business current account.
Tide business account plans and pricing (checked directly on tide.co, 20 October 2026)
| Plan | Monthly fee | Bank transfers included | Invoices/month | Card FX fee | Savings rate (Instant Saver) |
|---|---|---|---|---|---|
| Free | £0 | 5 | 3 | 2.75% | 1.5% AER |
| Smart | £12.49 | 30 | 3 | 0% | 2.5% AER |
| Pro | £27.49 | Unlimited | 3 | 0% | 3% AER |
| Max | £69.99 | Unlimited | Unlimited | 0% | 3.25% AER |
A few things worth knowing that aren’t obvious from the pricing page alone: Keep these in mind as you read the rest of this Tide business account review, since they change the real monthly cost more than the headline plan price does.
- Invoicing is capped at 3/month on every plan except Max. If you send more than three invoices a month, even Tide’s £27.49 Pro plan won’t lift that limit, only Max does. This is easy to miss because it looks like a “free plan” restriction, but it isn’t.
- CHAPS payments (same-day, higher-value transfers) aren’t available at all on Free or Smart. Pro includes 2/month, Max includes 5/month.
- Accounting software integration (a Xero connector) is available on every plan, including Free. “Tide Accounting”: Tide’s own built-in bookkeeping tool, is only included on Pro and Max. If you’re still choosing accounting software, see our FreeAgent vs Xero comparison for sole traders.
- New customers on any paid plan currently get a 1-month free trial, per Tide’s own site, worth using before committing if you’re on the fence between Free and Smart.
- Tide’s own pages don’t publish a specific per-transfer fee once you go over your plan’s included transfers, or specific ATM/cash-deposit charges. We’re flagging that gap rather than guessing a number, check the current fee schedule in-app before relying on a figure you’ve seen elsewhere, since several third-party review sites quote different numbers for this.
What the Tide business account costs a typical freelancer
Pricing tables don’t tell you where your own break-even point is. Here’s a rough worked example for a freelancer sending 15 invoices and making 10 outgoing payments a month:
- On Free: you’d blow through both the 5-transfer and 3-invoice limits well before the month is out. Once you’re over, you’re either paying per-transaction fees Tide doesn’t publish upfront, or manually batching payments to stay under the limit, both are a hassle at this volume.
- On Smart (£12.49/month): the 30 transfers comfortably cover 10 payments, but you’re still capped at 3 invoices, so this plan doesn’t solve the invoicing bottleneck, only the transfer one.
- On Max (£69.99/month): this is the only plan where 15+ invoices stop being a constraint at all.
The practical takeaway: if invoicing volume is your bottleneck instead of payment volume, the mid-tier plans won’t fix it. You’re choosing between Free/Smart with a workaround (invoicing through a separate free tool) or paying for Max specifically for the invoice cap rather than the transfers.
Which Tide plan is cheapest for you?
The right plan is set by three numbers: transfers you send, invoices you raise and cash you pay in. Enter yours and the tool prices all four plans for a year, using the 20p over-allowance transfer fee and the Post Office cash rates.
Invoices above three a month are only possible on Max, so plans that cannot do your volume are flagged rather than priced. Figures from tide.co, October 2026.
If the answer comes out as Smart or above mainly because of transfer volume, it is worth checking our sole trader bank account comparison: Starling, Monzo and Mettle all include unlimited free UK transfers on their £0 plans.
Is your money actually safe with Tide?
This is the part most reviews either skip or get out of date on, so here’s the current, checked position.
Tide’s business current account funds are protected by the Financial Services Compensation Scheme (FSCS) up to £120,000, this limit rose from the previous £85,000 on 1 December 2025, so if you’ve read an older review quoting £85,000, that figure is now out of date.
One exception: some older Tide accounts are e-money accounts (sort code 23-69-72, provided by PrePay Technologies). Money in those is safeguarded rather than FSCS protected. If your sort code starts 23-69-72, check in the app which type you have. Accounts opened today are ClearBank accounts.
There’s a nuance specific to sole traders that’s worth knowing: FSCS treats a sole trader’s business and personal deposits at the same authorised institution as one combined claim rather than two. So if you’re a sole trader trading as, say, “J Smith Consulting,” your business account balance and any personal deposits you hold with the same underlying institution are capped together at £120,000 total, not £120,000 each.
A limited company, by contrast, is a separate legal entity and gets its own independent £120,000 protection on top of the owner’s personal cover. If you’re deciding between staying a sole trader or incorporating and you regularly hold high cash balances, this is one more factor worth knowing, not just a tax one.
Tide business account pros and cons
Every Tide business account review comes down to the same trade-offs. Where Tide holds up well:
- Genuinely free tier exists with no minimum balance or turnover requirement
- Fast, mostly app-based account opening
- Xero integration on every plan, including Free
- Competitive savings rates that scale with your plan tier
- No FX fee at all once you’re on a paid plan
Where it doesn’t:
- The invoicing cap (3/month) applies to every plan except the most expensive one: an easy detail to miss
- No CHAPS on the two cheapest plans
- Not a bank in the traditional sense: some sole traders are more comfortable with a name they recognise as a high-street bank, even though the FSCS protection mechanics work out the same either way
- Tide doesn’t publish clear fees for exceeding transfer limits or for ATM/cash use, which makes it harder to budget precisely if your volumes fluctuate month to month
Who should probably look elsewhere
No Tide business account review would be complete without saying who it doesn’t suit. If you regularly deal in cash and need predictable, published cash-handling fees, or you specifically want a branch you can walk into, Tide isn’t built for you, and to be fair to Tide, it doesn’t claim to be. If you need an overdraft facility, that’s also not something Tide offers.
And if invoicing more than three times a month matters to you and £69.99/month for Max feels steep just to unlock that, it may be cheaper to stay on Tide Free/Smart for banking and use a separate free invoicing tool for the extra volume, worth doing the maths for your own situation instead of assuming Max is the only fix.
Tide business account: frequently asked questions
Is a Tide business account free?
Yes, the Free plan has no monthly fee, but it comes with real limits: 5 bank transfers and 3 invoices a month, plus a 2.75% fee on international card payments. For very light usage it’s free; past that, you’ll want to check whether Smart, Pro or Max solves your specific bottleneck (transfers vs invoicing) before upgrading.
Is Tide safe, is it FSCS protected?
Yes. Tide isn’t a bank itself, but your funds are safeguarded through its banking partner ClearBank and protected by the FSCS up to £120,000 (current limit since 1 December 2025). Sole traders should note this cap is combined with any personal deposits held at the same institution rather than separate.
Can sole traders and freelancers use Tide?
Yes, Tide is open to sole traders, freelancers and limited company directors with a UK-based business, provided you’re over 18 and can supply valid photo ID and a selfie for verification.
Does Tide work with Xero or other accounting software?
Yes, a Xero connector is included on every plan, including Free. Tide’s own built-in “Tide Accounting” tool is included on the Pro and Max plans only.
This review is based on Tide’s published pricing and terms as checked directly on tide.co on 20 October 2026. Fees and plan features can change: always confirm current terms on Tide’s own site before opening an account. This is general information rather than personalised financial advice; speak to an accountant or financial adviser if you need advice specific to your situation.
Decided Tide fits? The banner below is a partner link: if you open an account through it, Tide pays us a fee. It costs you nothing and has not changed anything written above. See our affiliate disclosure.
Tide is a business financial platform, not a bank. Current accounts are provided by ClearBank Ltd, which is authorised by the Prudential Regulation Authority and regulated by the Financial Conduct Authority and the Prudential Regulation Authority.
Comparing Tide against the other free accounts? We have separate reviews of Starling, Monzo, Mettle and Revolut Business.
Want to pay yourself a salary from irregular income?
Freelancer Money System 2026/27. Seven modules and five working sheets that pay you a predictable monthly amount out of unpredictable income: the account structure, the percentages, and where every pot should sit.
- A salary set from your trailing twelve-month low, not the average, with the calculator that finds it
- The day-it-lands allocation split, so tax and costs are moved before you can spend them
- The written drought plan for a bad quarter, the FSCS licence checker, and the surplus waterfall for a good year
Normal budgeting assumes a payday. Freelance income does not have one. The fix is not discipline, it is structure, and structure is a one-afternoon job.
Buying more than one? All ten 2026/27 courses for £107, against £293 bought separately.
Sources
This is general information, not financial advice. Pricing and terms are the provider’s own and change, check the linked pages before you rely on them.
Related guide — how to find your UTR.