

Bank charges, overdraft and credit card charges, card processing fees and interest on business borrowing are all deductible. Until 6 April 2024 the cash basis capped the interest deduction at £500 a year, and a great deal of published advice still says so. That restriction was removed entirely, along with the turnover limits and the loss relief restriction. What is never deductible: the capital you repay, and the interest HMRC charges on your own tax bill.
Are bank charges tax deductible for the self-employed? Yes, and so is the interest on money the business borrows. This is one of the least contested categories there is.
It is also one where the rules changed recently enough that a lot of what you will read is describing a system that no longer exists.
Which bank charges go where
The self-employment pages split this across two boxes. Box 25 is interest on bank and other loans, which HMRC’s notes describe as any interest on bank and other business loans, fees for buying goods and hire purchase. Box 26 is bank, credit card and other financial charges: any bank, overdraft and credit card charges, hire purchase and lease interest, and alternative finance payments.
Both notes end with the same instruction and the same warning.

Capital repayments are not bank charges
HMRC says it twice, once under each box, which tells you how often it happens.
When you repay a loan you are handing back money you were lent. Nothing has left the business. The cash goes out and the debt goes down by the same amount. Only the interest is a cost. A monthly direct debit of £420 that is £380 capital and £40 interest is a £40 deduction, and the temptation to enter £420 is exactly why the note exists.
The same logic covers hire purchase. The interest and charges go through; the payments buying the asset do not.
The £500 interest cap has gone
This is the part worth updating your notes for.
Before the 2024/25 tax year, a business using the cash basis could deduct no more than £500 of interest in a year, however much it actually paid. For anyone with a business loan that was a real restriction, and it was one of the main reasons advisers steered people towards traditional accounting.
The government’s own wording: the measure removes this interest restriction entirely, allowing businesses that use the cash basis to deduct any amount of interest as long as it is incurred wholly and exclusively for the purposes of the trade.
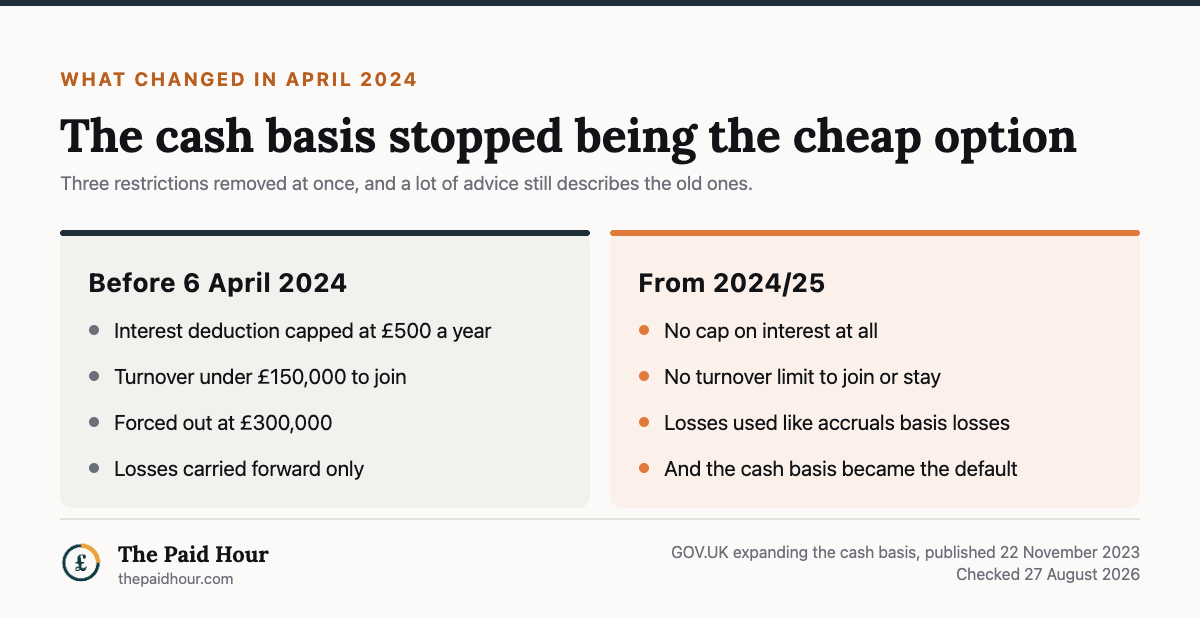
Two other restrictions went at the same time. The turnover limits (under £150,000 to join, out at £300,000) were abolished, so a business of any size can now use the cash basis. And cash basis losses can be used the same way accruals basis losses are, rather than only carried forward against the same trade.
Taken together those three changes are why the cash basis went from a scheme for the very small to the default for everyone. If you were told years ago that the cash basis was not for you, the reasons you were given may all have expired.
The bank charges box nobody fills in
Both notes carry the same sentence: if you used any part of your loan, overdraft or finance payment for non-business use, put the non-business part in box 40 or box 41.
That is the disallowable column, and it is HMRC quietly telling you how it expects mixed borrowing to be handled. You put the whole cost in the expense box and then take the private share back out, rather than guessing a net figure. It makes the working visible, which is precisely why it is worth doing that way round.
This matters most if you run the business through a personal account. The charges on that account are not wholly business charges, and the honest treatment is a proportion, which is one of several arguments for a separate business account, even though nothing in law requires a sole trader to have one.
Card processing fees, and where they go
The percentage a payment provider keeps is a financial charge and belongs in box 26. It is a real cost that never appears in your bank account as a payment, because it is netted off before the money arrives, which is how it ends up unrecorded in a lot of sets of accounts.
If you invoice £1,000 and receive £982, your income is £1,000 and your expense is £18. Recording £982 as income and nothing as a cost gets you to the same profit and an understated turnover, which matters for the VAT threshold if you are anywhere near it. More on the fees themselves in what card payments actually cost a freelancer.
Interest on your tax bill is not one of your bank charges
Box 25 is for interest on business loans. Interest HMRC charges you for paying your tax late is not that. It is a personal liability, in the same category as the late filing penalty, and neither is deductible.
Interest on a Time to Pay arrangement is the same interest, so the same answer. Which is worth knowing before you decide whether to borrow commercially to clear a tax bill: the commercial interest would be deductible and HMRC’s is not, and that changes the real cost of each option rather more than the headline rates suggest.
What HMRC may ask to see
Loan statements that split capital from interest, not just the direct debit amount. Merchant statements showing gross takings and fees, not the net settlement. And, if any borrowing was partly personal, the proportion and how you arrived at it.
The full list of what else goes through is in allowable expenses for UK freelancers, and the things that do not in disallowable expenses.
Want the whole tax system, not one rule?
HMRC Tax & Expense Mastery 2026/27. Nine modules and eleven working templates that take a UK freelancer from “do I even need to register” to a correct return, with MTD quarters built in.
- Fifteen expense categories, with the trap inside each one (training, clothing, meals, the seven-year pre-trading rule)
- Home and vehicle: flat rate against actual cost, with the £312 break-even worked out and the mileage lock-in rule
- The year-one payments-on-account cash shock, and the routine that stops it landing twice
HMRC does not send a list of what you forgot to claim. Most freelancers leave several hundred pounds of legitimate expenses on the table every single year, and the return still gets filed.
Buying more than one? The Complete Freelancer System, all five for £87, against £193 bought separately.
Sources
- Expanding the cash basis, GOV.UK, published 22 November 2023
- Self-employment (full) SA103F and notes, GOV.UK
- Cash basis: overview, GOV.UK
- Expenses if you are self-employed, GOV.UK
The box 25 and box 26 wording, including the instruction to put the non-business part in box 40 or 41, is quoted from HMRC’s notes to the SA103F self-employment pages, reference 12/25. The removal of the £500 interest restriction, the £150,000 and £300,000 turnover limits and the loss relief restriction is quoted from the measure published on 22 November 2023 and last updated on 14 August 2026. All pages read on 27 August 2026. This is general information about how the rules work, not tax advice. Check your own position with HMRC or an accountant before you file.